News
Dear Canada: It's Time For Open Banking
It might sound esoteric – or even boring. But the policy being considered by the government right now could radically improve our financial lives.
Wealthsimple makes powerful financial tools to help you grow and manage your money. Learn more
Dear Canada:
You've probably noticed that the financial industry doesn't work as well as a lot of other industries. Maybe you've experienced how hard it is to transfer money from one bank to another online; maybe you've been frustrated by all the forms and signatures and PDFs required to simply move your retirement account from one place to another; it's even possible you've noticed how long it takes to get another financial institution to transfer an account to Wealthsimple — they can take up to six weeks! How could a system that's so slow, so archaically manual, possibly survive in a world in which we expect almost everything to be doable with the tap of a smartphone? The answer is that it shouldn't survive — and that it won't.
Why am I bringing this up now? The Canadian government is currently reviewing something called “Open Banking” and deciding if it's something Canada should implement. Maybe Open Banking sounds a little dry. Or maybe it sounds scary, like suddenly all your credit card statements will be made public (don't worry; it's nothing like that). But it's actually a rare chance, at a really important time, for Canada to fundamentally change how we do money in this country for the better.
Now you're probably wondering exactly what Open Banking is. Essentially, it's a set of objectives for how the banking system should work. There are a few important improvements it proposes, but let's stick to the part that the Canadian government is currently reviewing: information sharing. Open Banking would mean that you decide how, and when, and with whom to share your financial data. A lot of people think that's already the way it works — but they're wrong. What it absolutely would not mean (though it's how those folks who are opposed to Open Banking spin it, probably to scare you) is banks being forced to give customer data to anyone who wants it — privacy and security be damned. That would be a disaster for everyone, especially companies like Wealthsimple.
The truth is that banks already share your information with third parties all the time. That's how, for instance, they keep your credit card's loyalty program up to date on what you've been up to. But under the current system, it's at the banks' discretion as to when to share that information, and with whom. Open Banking would mean that you would decide whether and when to share your information, whether it's with a different bank, your accountant, or a fintech company like ours.
You may be wondering why the current system — slow and haphazard as it is — exists the way it does today. It's partly because it's old and was never designed for the world we live in. And it's partly a way for financial institutions to protect their place in the world. If you were a bank that was benefiting from the status quo in the finance world, it would probably behoove you to make it easy for your customers to share information with businesses that make you look good, and difficult to share information with companies that make you a little nervous. Why make it easy for a customer to switch from your high-fee chequing account, for instance, to a bank with lower fees just because it's the best thing for your customer?
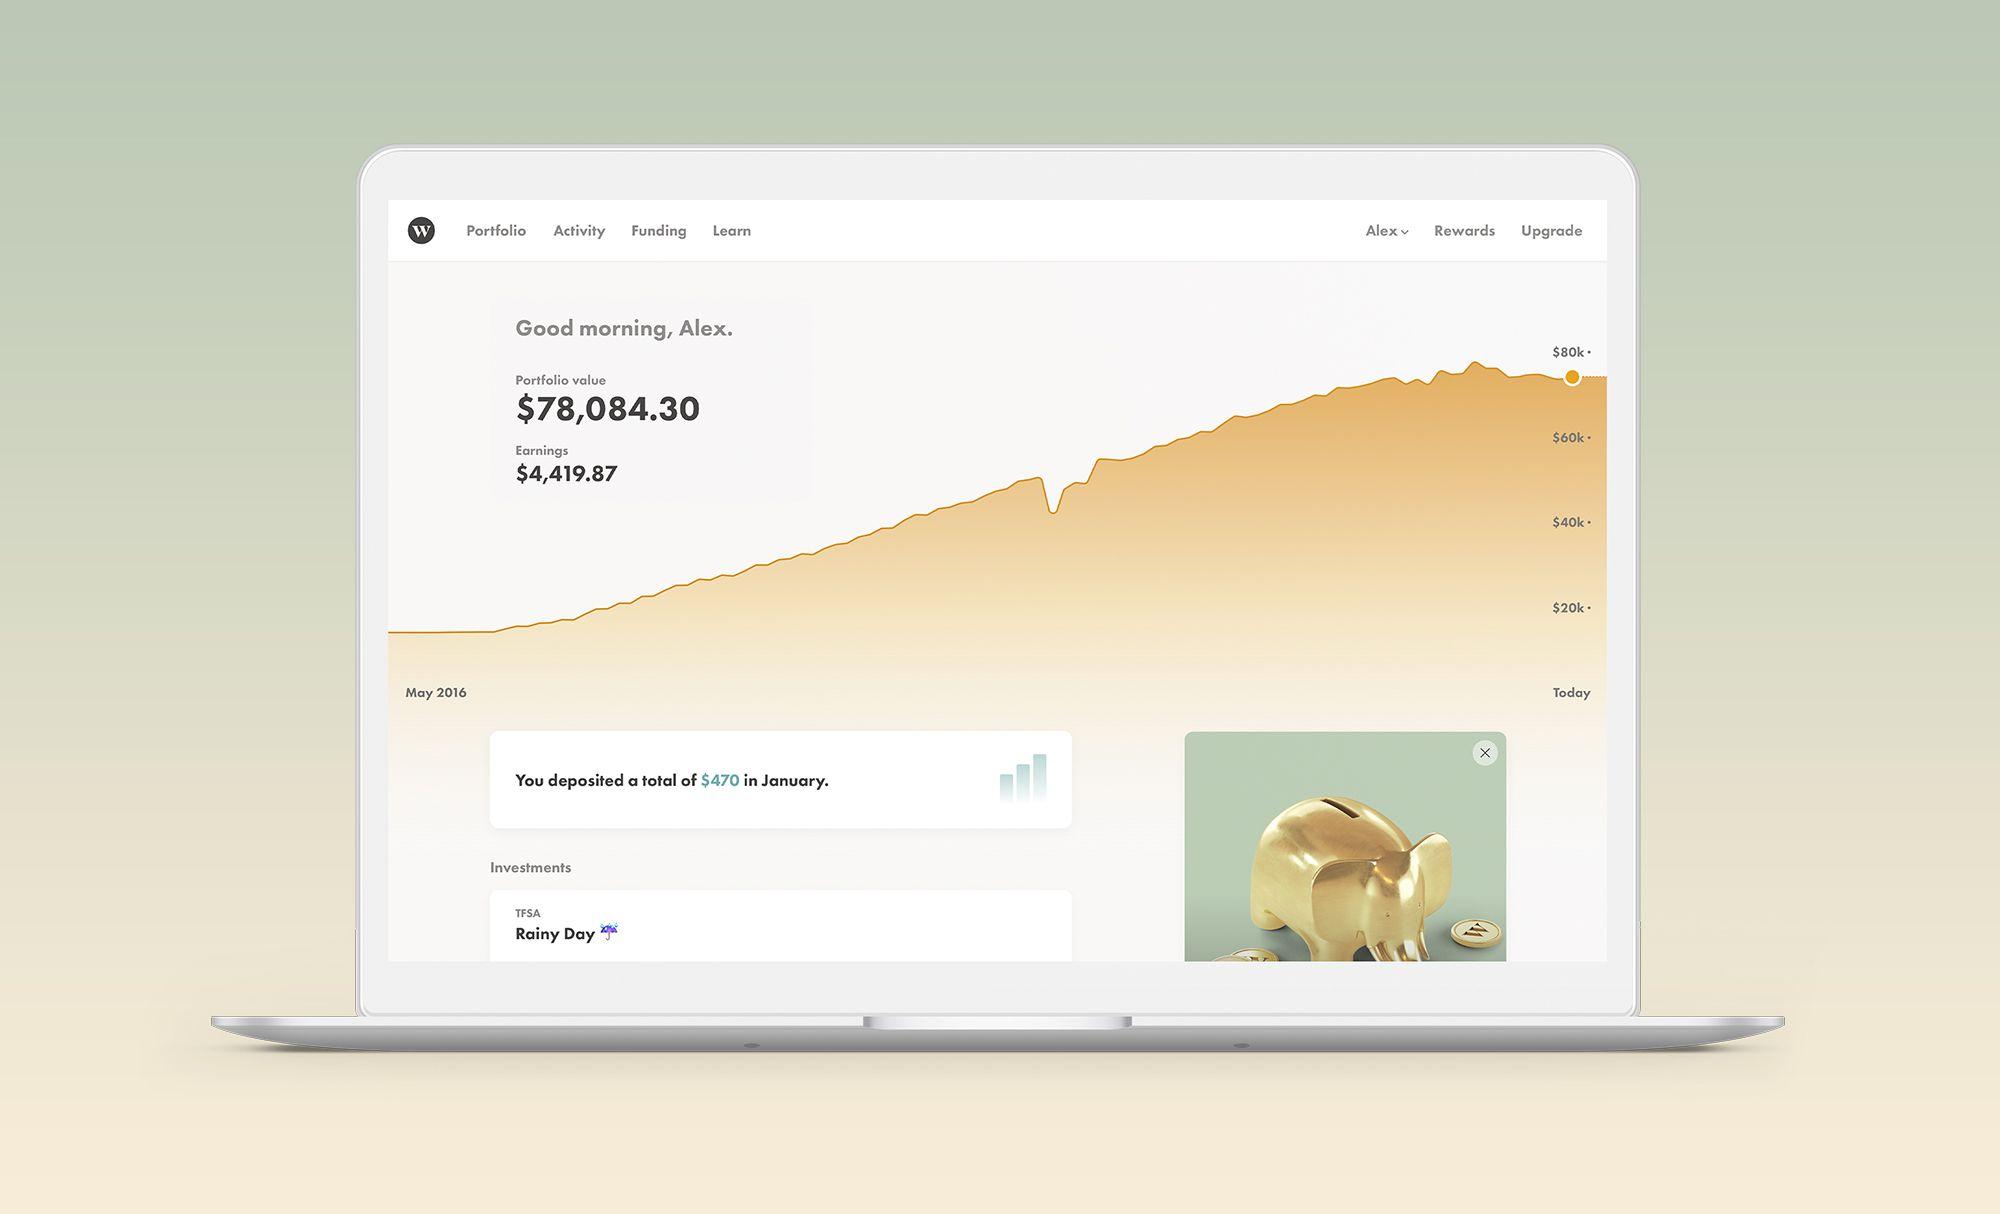
The effect of all this is that it's really hard for people to make choices based on what's best for them. Making the system sluggish and unpredictable also stymies competition—and innovation. I can tell you from firsthand experience that lack of access to data is one of Wealthsimple's biggest hindrances when it comes to making better products, and making them available to everyone. And when you have less competition and innovation, you end up with a financial system rife with some of the very highest fees in the developed world — as is the case in Canada. But if we had a system in which it were really easy to compare prices and features and fees, and just as easy to switch services with the tap of a phone, banks would really have to compete for your business. And they'd probably have to prioritize lining their own pockets a little bit less to do that. Open Banking would mean a general upward slope on the joy graph and a downward slope on the pain graph when it comes to your financial life.
But this is also about the future of our economy and our country. At the end of the day, I don't think anyone can stop progress and innovation in the financial world—or anywhere else for that matter. Open Banking is already being implemented in the UK and Australia, among other places. The underlying question is what would happen to Canadian companies in a world in which other countries are innovating faster? Because better, simpler and more efficient products tend to win. The way I can see it, we can either keep the system we have and be importers of new services, built in other countries; or, we can create the environment we need to build world-beating products here. It won't surprise you to hear I'm in favour of option two.
I don't think there's a reason anyone can offer in good faith to oppose Open Banking. The arguments I hear against it strain credulity — maybe bigger institutions just don't have confidence in their own tech and innovation; or maybe they believe stopping Open Banking is good business for them. Some folks say they're worried about the security of your data — which is of course a huge priority for us, as well. But an Open Banking system isn't any less secure. It would, in fact, drive banks and financial companies to upgrade to newer, more secure technology.
It's true that Open Banking is in the best interest of companies like Wealthsimple that want to change the competitive landscape in the financial industry. But that's not at the root of why we support it. Our company is predicated on offering better, smarter and less expensive services (with superior, simple software) so that people want to move their money to Wealthsimple accounts if they decide it's better for them. It's that last part that's important: it should be up to you to put your money where you think it serves you. And no one should stand in the way of that.
Illustration by Jenny Mörtsell.
Written By
The Editors
Wealthsimple's education team is made up of writers and financial experts dedicated to making the world of finance easy to understand and not-at-all boring to read.