Finance for Humans
We Just Bought Five Toronto Condos. Was It a Brilliant or Boneheaded Investment?
The real-estate market is a pillar of the Canadian economy. And since we just bought a handful of condos to give away, we decided to dig into where things stand for prospective buyers.
Wealthsimple makes powerful financial tools to help you grow and manage your money. Learn more
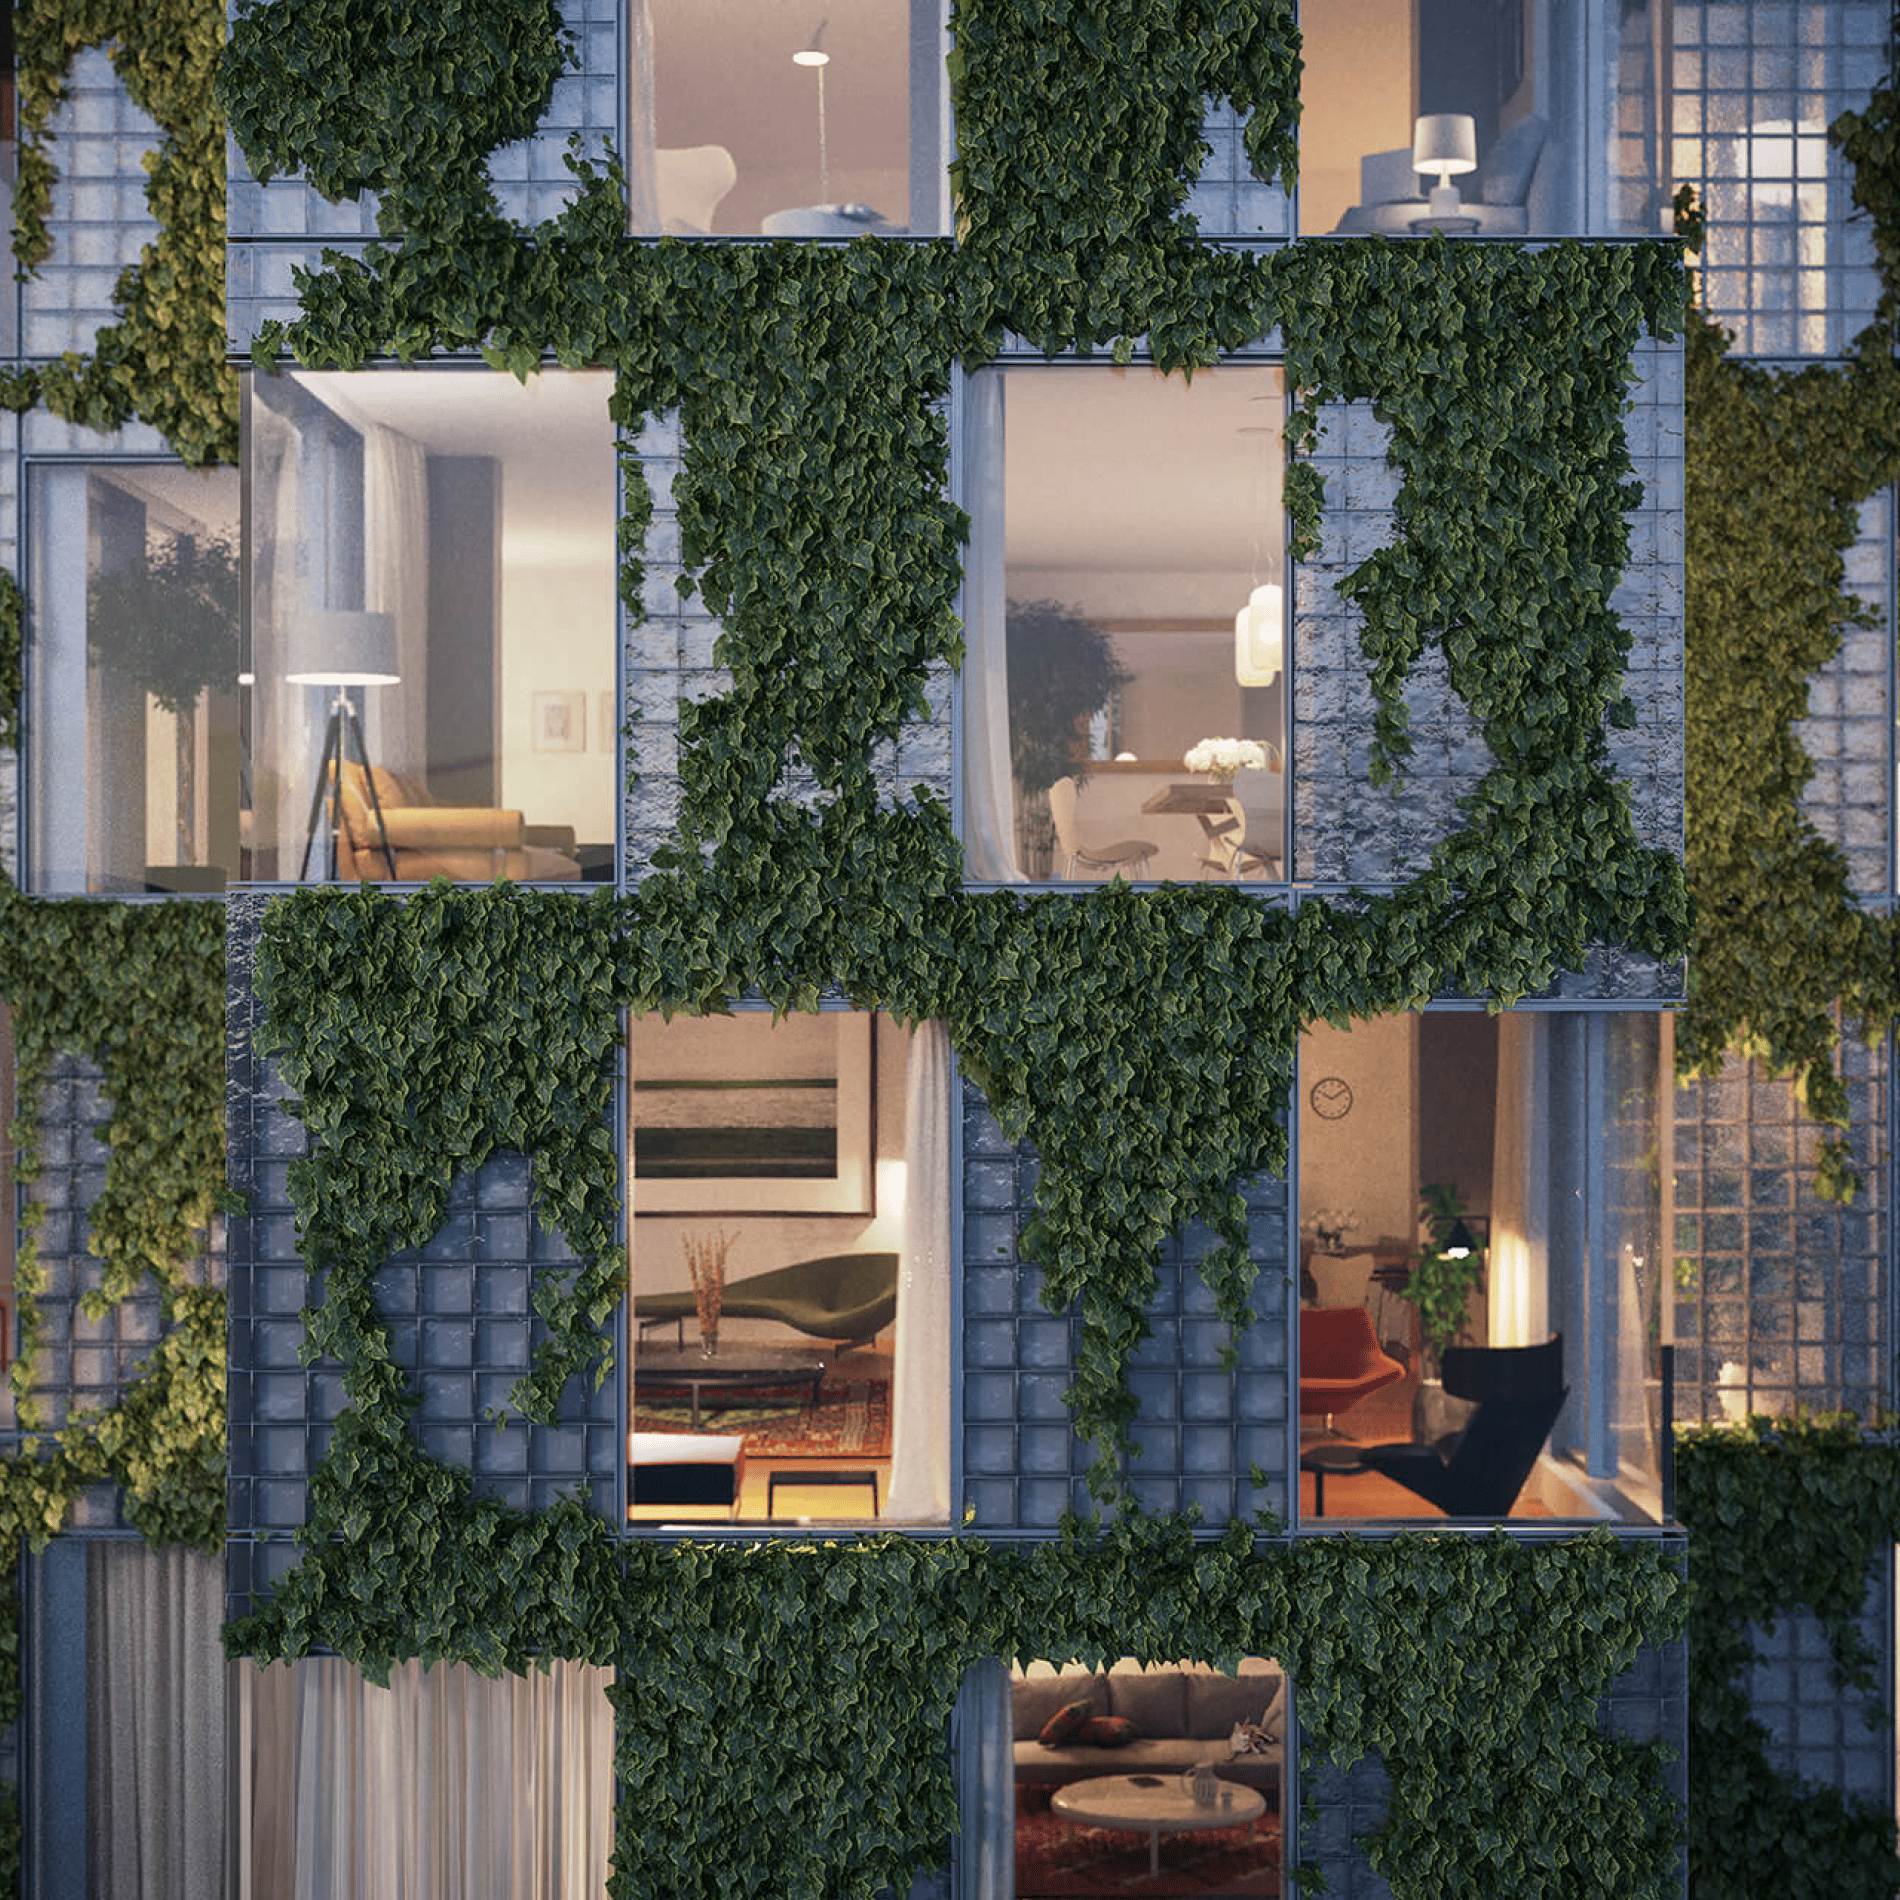
Wealthsimple recently bought five super-beautiful Toronto condos, and while they’d make great crash pads for our midnight-oil-burning advisors, we’ve decided to give them away, Oprah-style, to five lucky Monthly Millionaire winners.
You can read all about the contest here. But the gist is if you refer a friend to Wealthsimple, you get 100,000 chances (300,000 max) to win one of the condos, including an extra-swanky unit at KING Toronto. Pretty neat!
Obviously, we bought them for different economic reasons than most buyers — they aren’t a place for us to live, and they’re not an investment (though we hope they’ll be a windfall for the folks who get the keys).
Still, going through the purchase process made it clear that it’s an exceedingly tricky time to decide whether to buy. For starters, the market has crashed. From early 2022 to the second quarter of 2026, the price of an average GTA condo slid by almost 20%, from about $770,000 to about $634,000. Adding to the weirdness, dark economic clouds have appeared overhead in the form of the trade war, rising fuel prices, etc.
Then again, doesn’t the buy-low/sell-high chestnut suggest that a downturn is the perfect time to scoop up a discounted unit?
We decided to explore that question and whether, broadly speaking, it’s a good or lousy time to buy a GTA condo. And to figure it out, we used both math and some shoe-leather reporting. Here’s what we found.
Part 1: Do condos pass the rent v. buy test?
Finance 101 says that if you’re weighing whether to buy a home, you should turn to the price-to-rent ratio, which helps determine whether buying or renting is a savvier investment by taking the purchase price of a place and dividing it by the annual cost of renting a similar home. If the result is around or below 17, you’re better off buying; if it’s above 23, you should probably rent and invest in stocks and whatnot instead. And if you’re somewhere in the middle, it’s a coin toss.
According to the latest data from Condos.ca, the average asking price of a one-bedroom Toronto condo is around $577,000. With one-bedroom rents averaging $2,273 (or $27,276 per year) that puts the price-to-rent ratio at about 21 — firmly in shoulder-shrug territory.
Two-bedroom units, meanwhile, are listed for $895,000 on average, according to Condos.ca, while average rents are hovering around $3,000, or $36,000 per year. That puts the price-to-rent ratio at 25 — firmly in rent-and-invest territory.
So that’s the broad picture. But, before you write off buying, crunch the numbers for whatever property you’re considering.
Part 2: The 30% rule (or the how-much-do-you-make rule)
To ensure our math was aligned with reality, we reached out to Andrew Modrzynski, a senior advisor at Wealthsimple. “While prices have gone down, many people feel condo prices are still too high for what they get,” he said. Many folks simply don’t earn enough to cover the price of a condo, even at these reduced prices (in no small part thanks to high mortgage rates).
To his point, average full-time income in Toronto sits around $75,000, and most financial advisors warn against spending more than 30% of your pay on housing, which works out to about $1,875 per month on a $75,000 salary. If you put down 20% (or $115,400) on the average one-bedroom condo, your monthly mortgage note would come in at north of $2,500 — well above that 30% benchmark. And that’s not accounting for property taxes, condo fees, or rustic “Bless this Mess” signs.
A couple pulling two average incomes (so $150,000) would exceed the 30% benchmark, too, if they put down 20% on a $895,000 two-bedroom. Realistically, to afford that place, their annual household income would likely need to top $190,000 to cover the mortgage, building fees, maintenance, and taxes. And if said couple has children — well, those little tykes will make their budget tighter and probably require that the family spends less than 30% of their income on housing.
The good (or at least good-ish) news, Modrzynski says, is that in Toronto you can likely find a rental unit for a comparable bargain. “Don’t stretch yourself thin just to say you own property,” he adds. “There’s absolutely nothing wrong with renting in today’s market.”
Part 3: How long do you plan to stay?
Modrzynski says another big thing to consider is your time horizon. The longer you intend to live in a property, the lower the risk, so if you do want to buy, make sure you’re up for at least a five-year or ten-year commitment (preferably not with a “soulmate” you met last week on a dating app). That way, your home has ample time to appreciate and recover from short-term market swings. His last warning: mentally prepare yourself for the possibility that the market might be sluggish when you decide to sell. “I can’t tell you how many people I've spoken to that purchased a condo in 2022 and had planned to sell, but are left holding the bag,” he says.
The Upshot: So did we make a good investment?
Whichever five lucky people win our giveaway condos (obligatory contest relink!) are almost certainly receiving a solid investment, since condo prices have already fallen so much and they’re paying zilch for the asset.
And if we had kept the condos for ourselves? Well, our entry point looks a lot better today than it would have a few years ago, and the condos are in desirable parts of town. So, there’s a good chance we would have come out alright. From 2000 to 2021, Canadian real-estate prices boomed, so perhaps this downturn is just a blip. Then again, in the mid-1970s and again in the 1990s Canadian home prices had flat or negative inflation-adjusted returns. “Line go up doesn’t always hold true in real estate,” as Modrzynski put it.
Which, annoyingly, is why it’s premature for us to say for certain whether our five condos would have been stellar or rotten investments had we kept them. Shaun Hildebrand, the president of real-estate research firm Urbanation, told us that he’s optimistic that demand will pick up in time. And when demand does accelerate, it will outrun supply, he says, since new construction is basically nonexistent. Which makes sense to us. The hitch is that no one knows when the market will hit bottom or turn around — which is why real-estate investing shares one very big trait with all other forms of investing: its rewards don’t come without risk.
Written By
The Editors
Wealthsimple's education team is made up of writers and financial experts dedicated to making the world of finance easy to understand and not-at-all boring to read.
No purchase required. Contest begins on Aug 27, 2026 at 12:00am ET and ends Sept 30, 2026 at 11:59pm ET. Open to Canadian residents who are age of majority in their province or territory of residence at the time of entry. 173,407 Prizes available to be won in Canada, consisting of: 5 Grand Prizes (Week 1: 1 x unfurnished condo at The Georgian (ARV: CAD$635,700); Week 2: 1 x unfurnished condo at The Georgian (ARV: CAD$783,900); Week 3: 1 x unfurnished condo at The Georgian (ARV: CAD$837,200); Week 4: 1 x unfurnished condo at Concord Canada House (ARV: CAD$699,900); Week 5: 1 x unfurnished condo at KING Toronto (ARV: CAD$1,454,990)); 173,402Secondary Prizes, each consisting of either a cash prize ranging in value from CAD$3 to CAD$100 (173,252 available) or a EQ3 Bird Swivel Chair (ARV: CAD$1,599) (150 available). Cash prizes to be deposited into a Wealthsimple Chequing account only. The Contest features 5 weekly Draws, with 1 Grand Prize and Secondary Prizes available to be won in each Draw week. Max. 300,000 entries per Entrant. Odds of winning depend on the total number of eligible entries received. Skill-testing question req’d. Georgian & KING condos pre-construction; anticipated occupancy Feb. & July 2027, subject to change. Grand Prizes awarded by assignment; winners must be legally entitled to acquire property in ON. Wealthsimple app & account req’d to receive a prize, there are no fees associated with such account or app. Full rules and entry details available at wsim.co/monthlymillionaire.