Finance for Humans
Why the Asset Bubble Popped, All at Once
A decade-long market frenzy came to a swift, painful end this year. We asked Philip Grant of Grant’s Interest Rate Observer — a financial newsletter that was one of the first publications to warn about the 2008 financial crisis — to explain why stocks and bonds tanked in tandem.
Wealthsimple makes powerful financial tools to help you grow and manage your money. Learn more
It’s the morning after in North America. The major stock indices finished the third quarter at or near bear territory, and bonds have provided no port in the storm: Bloomberg’s benchmark U.S. Treasury index shed 4.3% in Q3, bringing its year-to-date losses to a historically awful 13%. (Canadian Treasury bills finished the quarter flat.) This one-two punch has dealt so-called 60/40 investors — those who hold that classic portfolio allocation of stocks offset by (ostensibly) safer bonds — their worst annual showing since the Great Depression. Which has a lot of reasonable people wondering: why has this diversified, resilient portfolio failed to be, well, resilient?
Recommended for you
What to do when you're suddenly rich
Finance for Humans
Is the Stock Market Finally, Actually Overvalued?
Finance for Humans
Make Your Financial Life Bulletproof, With Help From John Goodman (?!)
Finance for Humans
The Easy-Money Era Is Over Markets are, in effect, enduring a bruising hangover from a long-standing stimulus party. In the years after the 2008 meltdown, central bankers kept interest rates near zero to encourage lending and jump-start the economy. These low rates gave investors little reason to keep money in the bank, since zero rates meant zero interest payments. Cash was trash. Growth trumped profitability. Savers suffered, while borrowers basked in cheap money and low credit stress.
The result was a decade-long bonds-and-stocks frenzy that, in time, fomented a giant asset bubble — one that grew during the pandemic. Last year, by one measure, stocks reached their most expensive levels, relative to earnings, since the dot-com days. Demand for bonds, meanwhile, was so strong that a record $18 trillion of global debt slipped into the Upside Down, meaning that investors, desperate to put their money anywhere but in the bank, were willing to pay more for a bond than what they would receive when it matured. Buy $100 now; get back $95 in five years. But the thinking went that maybe the bond prices would appreciate with a little luck.
Higher rates have crushed stocks that soared during the zero-rate era, particularly those of fast-growing, unprofitable tech companies.
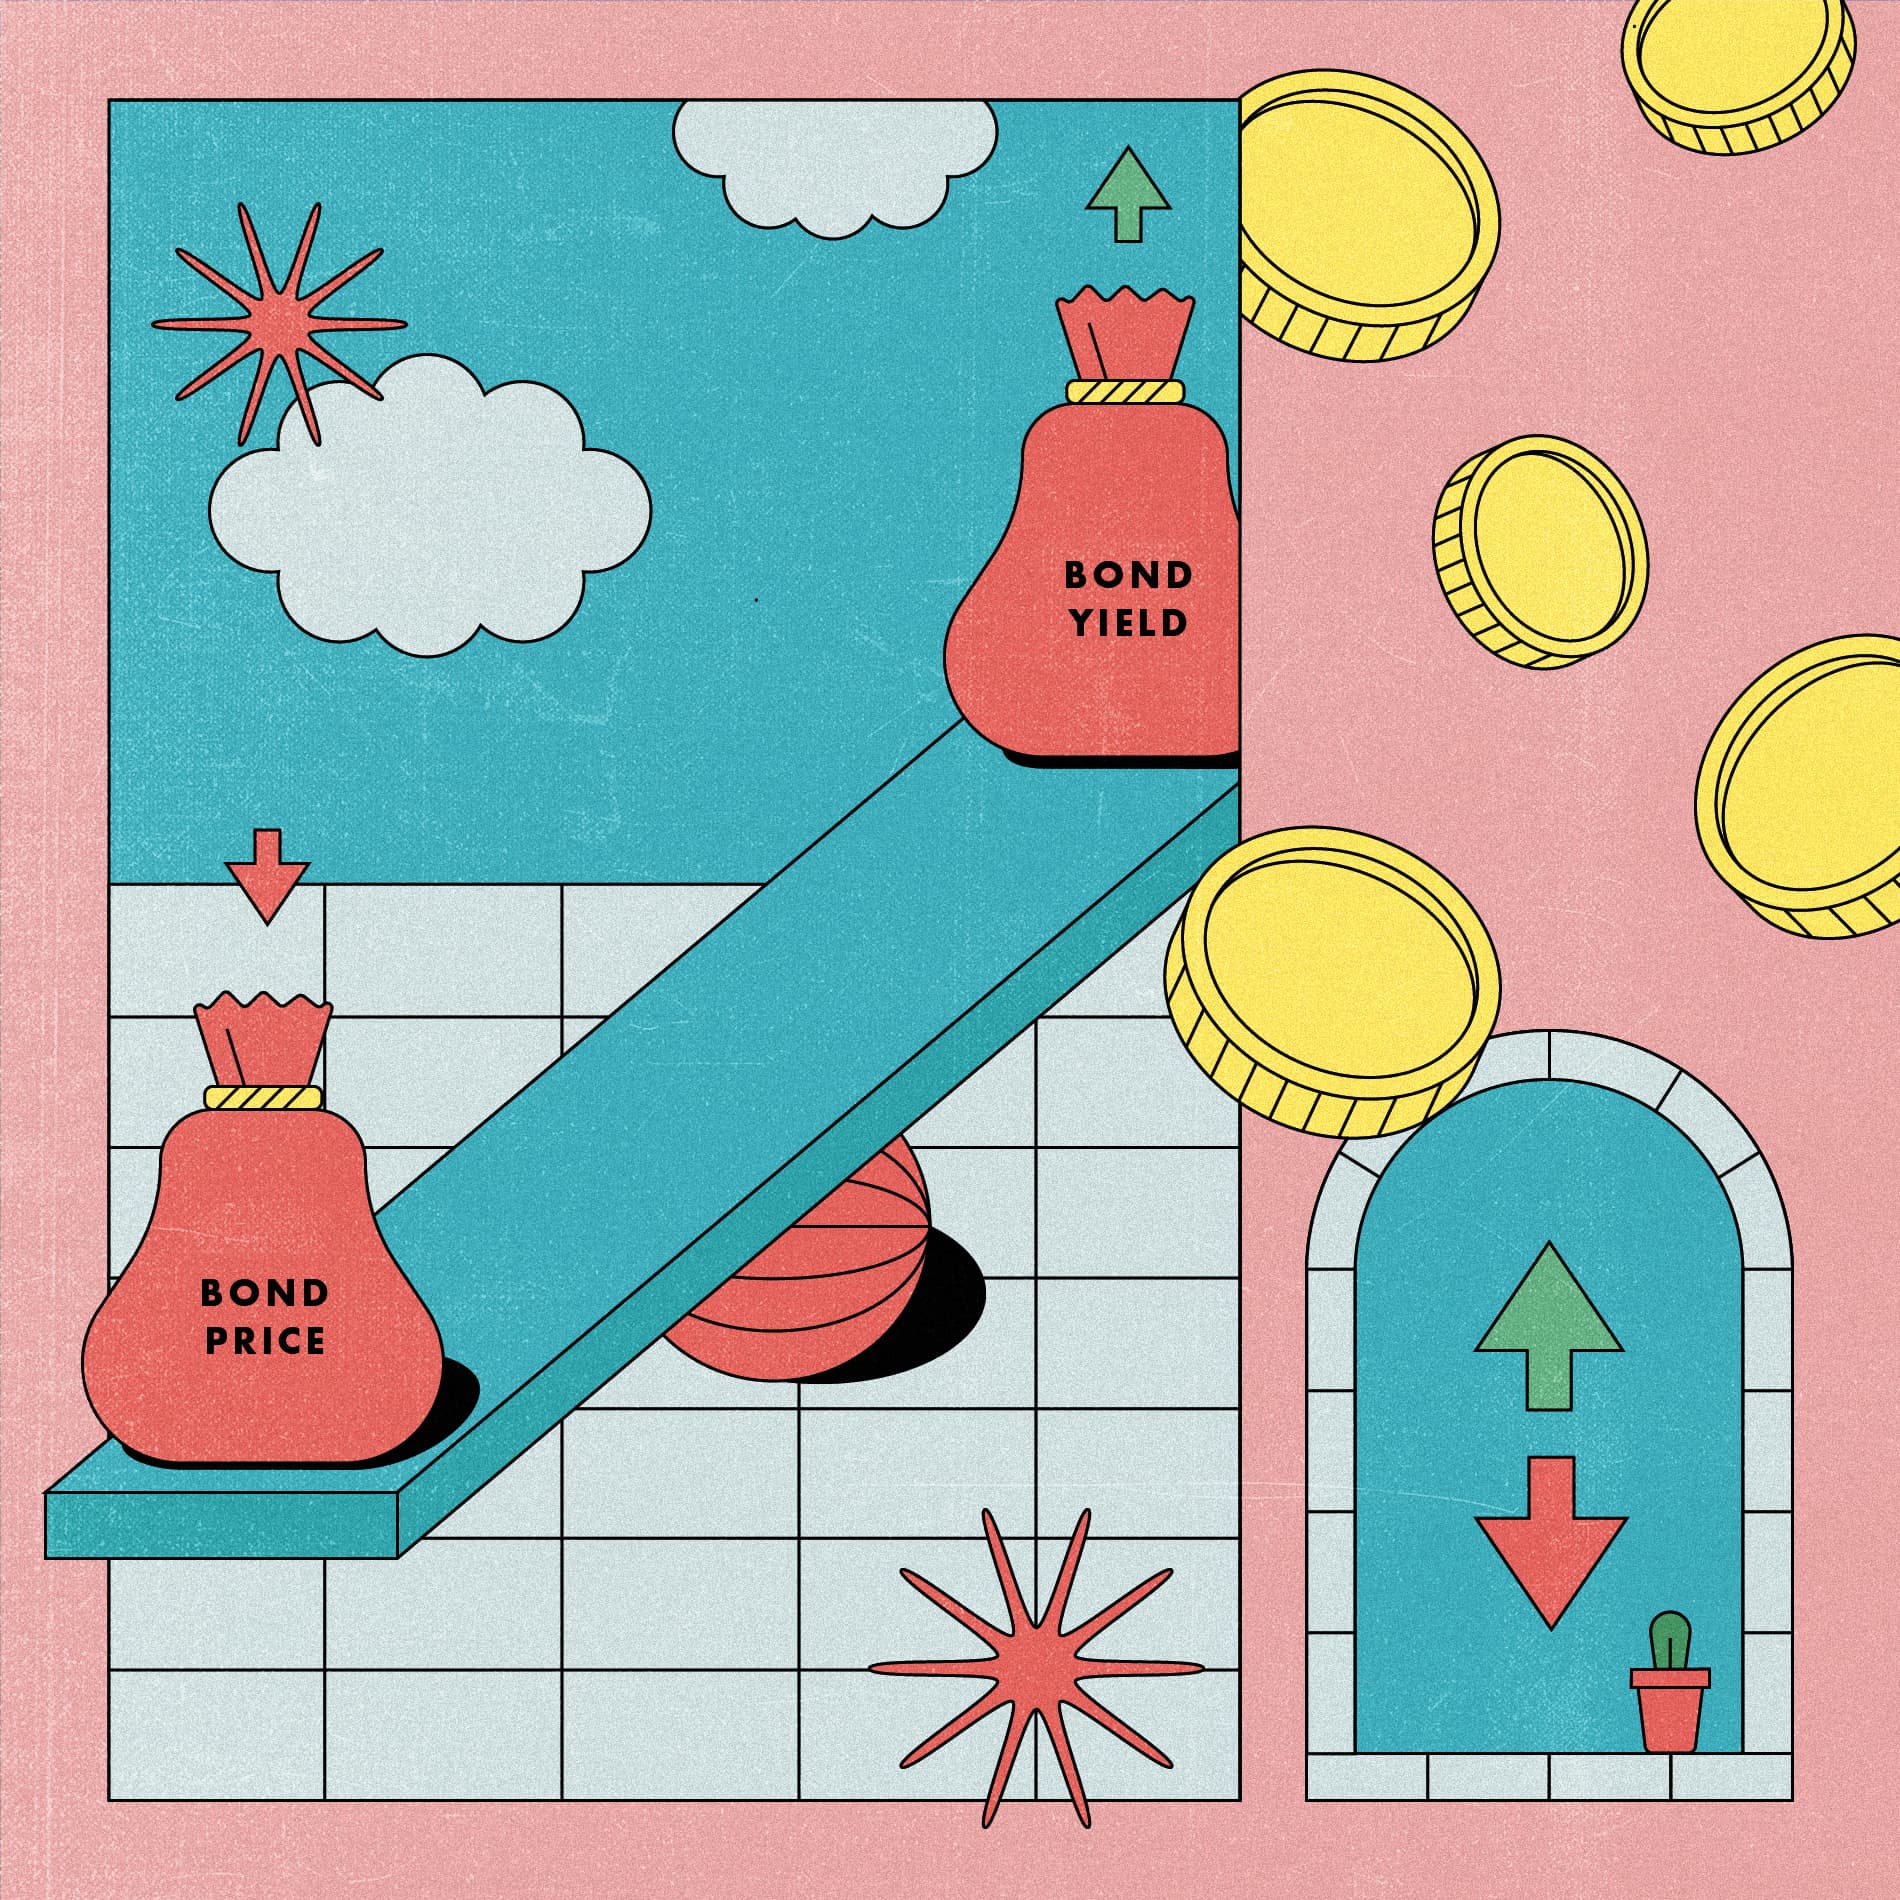
Interest Rates Triggered a Reckoning Now, raging inflation has forced central bankers to sharply raise interest rates to slow the economy. These higher rates have crushed stocks that soared during the zero-rate era, particularly those of fast-growing, unprofitable tech companies, like Shopify (down a cool 80% this year) or DoorDash (-70% YTD). Meanwhile, bonds, which have historically risen when stocks slide, haven’t dampened the blow, since rising rates pushed investors to hoard cash in (now juicy) savings and money-market accounts.
Could Q4 … Be Worse? As markets limp toward the 2022 finish line, one big question is whether policymakers will throttle back their rate-hiking campaign to control inflation. The U.N. has already called on central bankers to halt rate hikes to avoid a global recession. And high borrowing costs will constrain government spending, perhaps testing policymakers’ inflation-curbing resolve. So far, though, neither the Fed nor the Bank of Canada have signalled an end to the hikes and likely won’t in the very near future, following another hot U.S. inflation print last week. There’s a chance that inflation could start falling fast late this year or early next, as rising rates take their toll. But, provided prices stay stubbornly high, legendary investor Stanley Druckenmiller speculated on where this leaves us: “All those factors that cause a bull market, they’re not only stopping; they’re reversing.” This quarter, in other words, could be even more sobering than the last one.
Written By
Philip Grant
Philip Grant is the associate publisher of Grant’s Interest Rate Observer, a financial newsletter that, among its many distinctions, was one of the first publications to warn about the 2008 financial crisis.
The content on this site is produced by Wealthsimple Media Inc. and is for informational purposes only. The content is not intended to be investment advice or any other kind of professional advice. Before taking any action based on this content you should consult a professional. We do not endorse any third parties referenced on this site. When you invest, your money is at risk and it is possible that you may lose some or all of your investment. Past performance is not a guarantee of future results. Historical returns, hypothetical returns, expected returns and images included in this content are for illustrative purposes only.
Recommended for you
What to do when you're suddenly rich
Finance for Humans
Is the Stock Market Finally, Actually Overvalued?
Finance for Humans
Make Your Financial Life Bulletproof, With Help From John Goodman (?!)
Finance for Humans